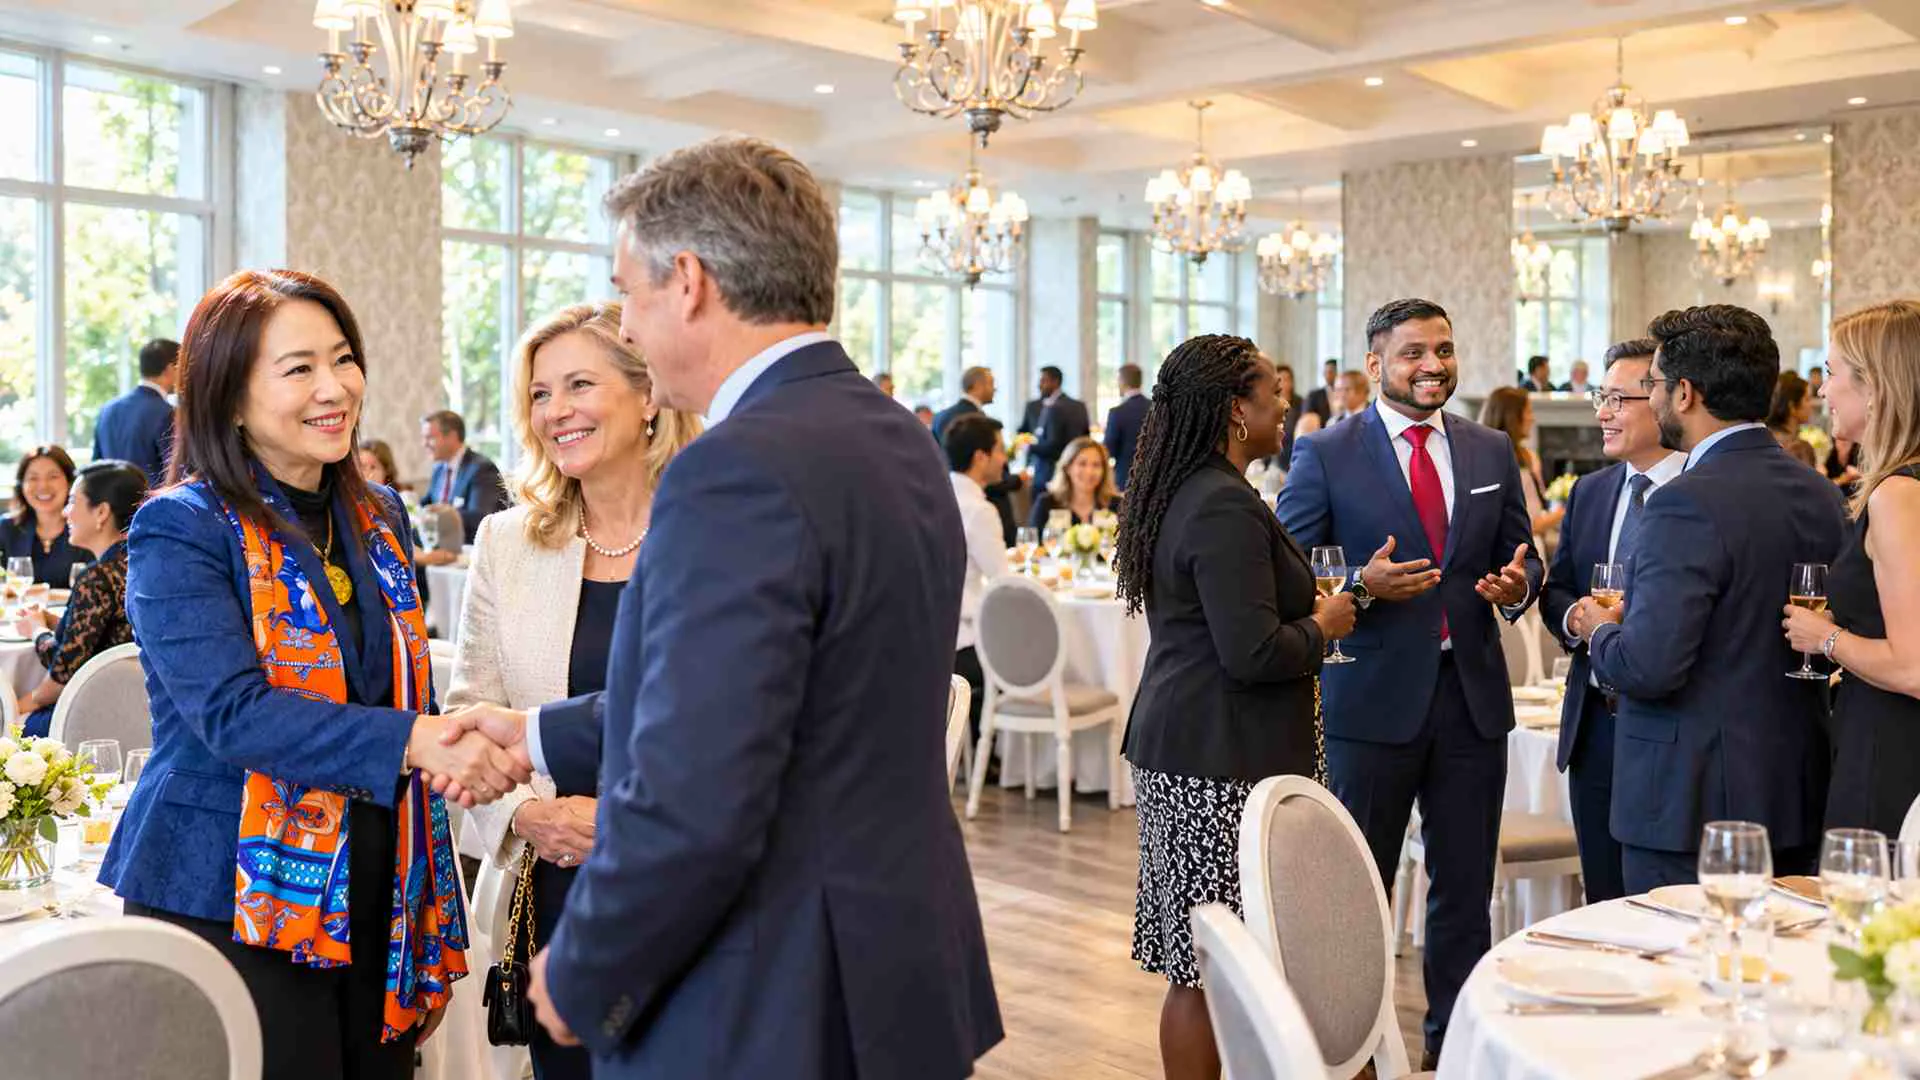
A private dinner for physicians and dentists in Durham
You have $1 million or more in your corporation. Taking it out could cost 47.74%. It does not have to.
Over dinner, our team from AT Financial Group will walk through the ways Ontario medical professional corporation's retained earnings become personal wealth. We will discuss tax efficient strategies, retirement planning using corporate funds, investments and using corporate funds to buy real estate investments.
This is for you if
- You are a physician, specialist or dentist practising in Ontario, incorporated or about to be.
- Your corporation holds, or will hold within five years, $500,000 or more you do not need to live on.
- Your TFSA and RRSP are full, or close to it, and you are wondering what the next dollar should do.
- You have heard "corporate-owned insurance", "IPP" or "capital dividend account" from a colleague and want to learn more.
- You are between roughly 35 and 60 and expect to practise for at least ten more years.
- Learn to buy investments and real estate from corporate earnings.
It is not for you if you are unincorporated with no plan to incorporate, or if you need every dollar the corporation earns. Say so on the form and we will point you to the right page instead.
See planning by career stage for physicians and for dentists.
Six things you will understand by dessert
Why the money is stuck
Retained earnings were taxed at 11.2% to 12.2% going in; as a non-eligible dividend they face up to 47.74% coming out, and investment income inside the corporation is taxed at 50.17% up front. We show the arithmetic on a $1.5 million balance.
The capital dividend account
The one account that pays out at 0%: how it fills from the untaxed half of capital gains and from life insurance, how a $1 million to $3 million balance is built over ten to twenty years, and what the T2054 election and the 60% penalty are.
Corporate-owned participating life insurance, and the borrowing strategies built on it
Immediate financing arrangements and corporate insured retirement plans: what the deductions are, what lenders require, and the four ways they go wrong.
Pensions for incorporated professionals
Individual pension plans, HOOPP for Ontario physicians, and Medicus, against the RRSP, with the 2026 room at 40, 50 and 60.
The tax at death, and the three fixes
Why a corporation can be taxed at over 70% at death without planning, and how a loss carry-back, a pipeline or insurance through the capital dividend account brings it to roughly a quarter to a half.
Residential real estate investments
Where a rental property should sit and why: in your own name or a holding company, never in the professional corporation. Rent inside a corporation is taxed at 50.17% and counts toward the $50,000 passive income threshold; the untaxed half of a gain goes to the capital dividend account; and the home you live in stays in your own name, since the principal residence exemption is personal. We work the 2026 cash flow on a Durham Region rental.
Every figure is Ontario, tax year 2026, with the source on the handout.
What we will not do
- Name a carrier or a product as "the best".
- Ask anyone to sign anything at the table.
- Show a case study without saying it is an illustration.
- Promise a tax result. Nobody controls the CRA, and we say so.
An illustration we will work through together
| Dr. B, 46, incorporated specialist, Whitby | |
|---|---|
| Retained earnings today | $1,400,000 |
| Added each year | $150,000 |
| Registered accounts | TFSA and RRSP full |
| Investment income in the corporation next year | about $60,000, above the $50,000 threshold |
| What we compare | (a) keep investing in the corporation; (b) pay dividends and invest personally; (c) fund a corporate participating policy for 20 years and build the capital dividend account; (d) an IPP |
| What you take home | a one-page comparison with after-tax outcomes at 65 and at death under each, with the assumptions written down |
Bring last year's T2 and your corporate statements and we will use your figures instead of Dr. B's, privately, in the 30-minute follow-up if you want one.
Your hosts
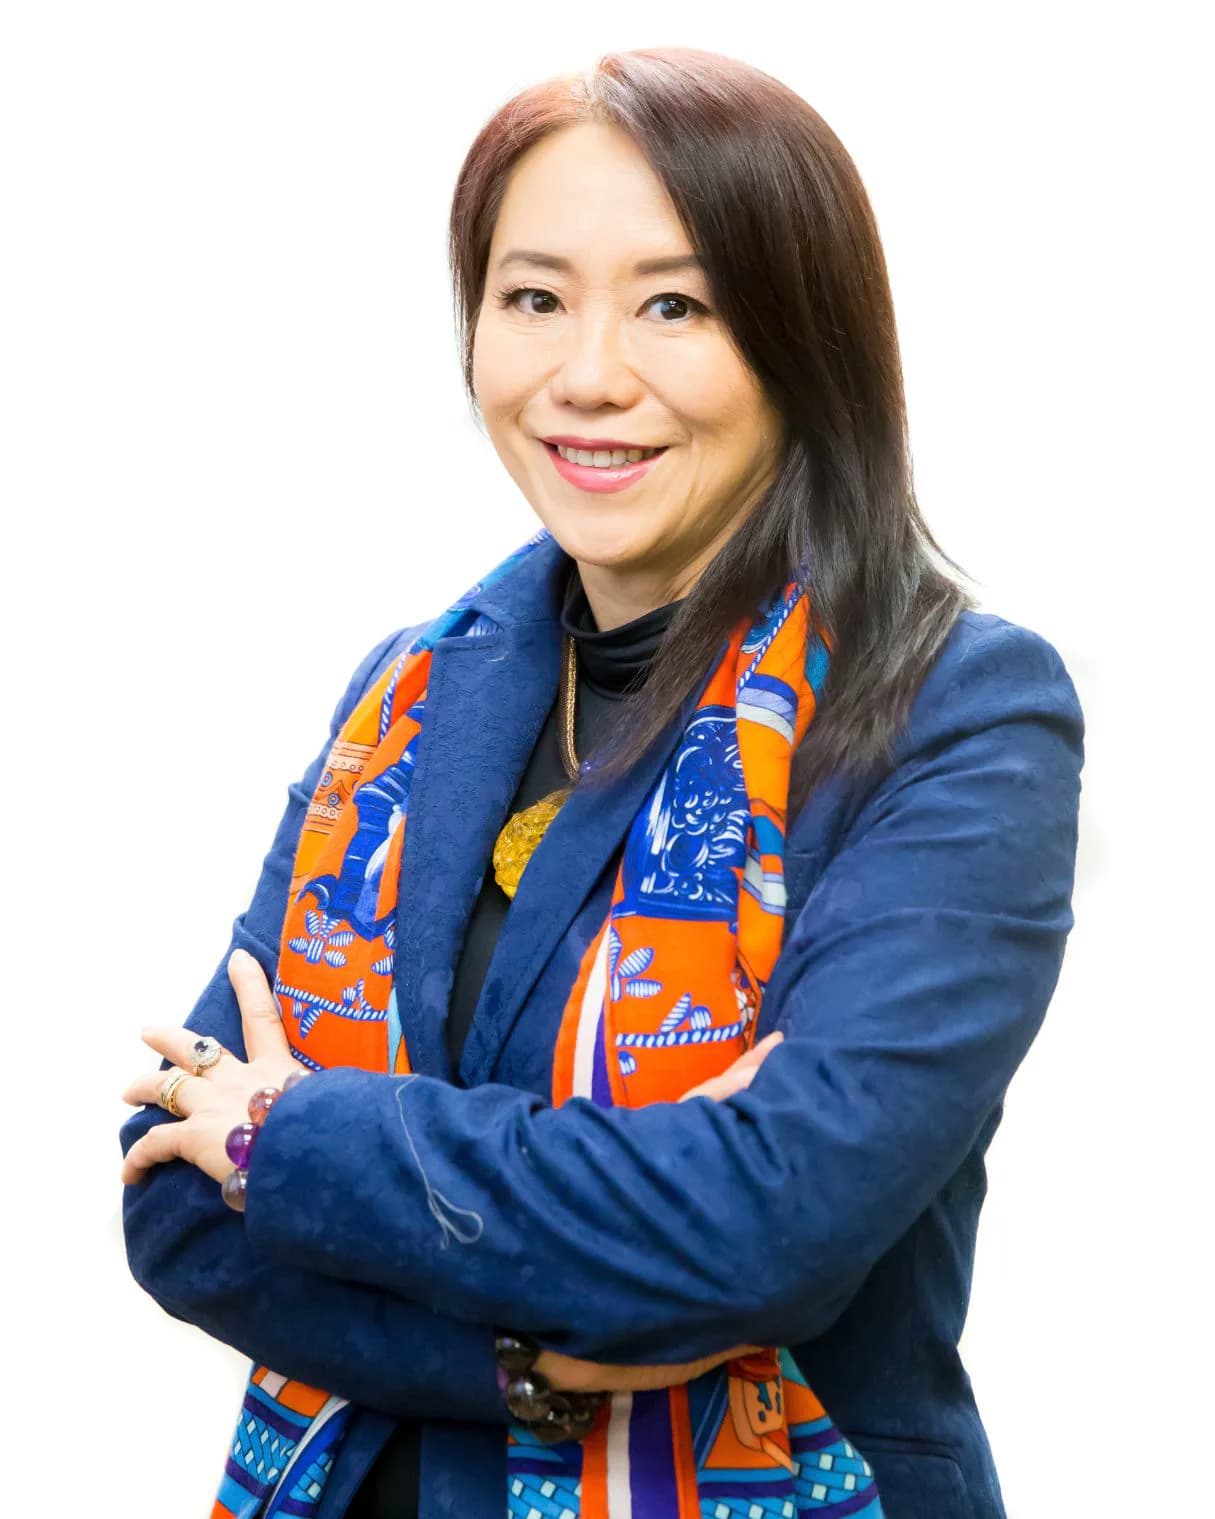
Amy Tong — President, AT Financial Group. Specializes in disability, life, critical illness and investment planning for healthcare professionals; reviews every advice page on beyondthepractice.ca.
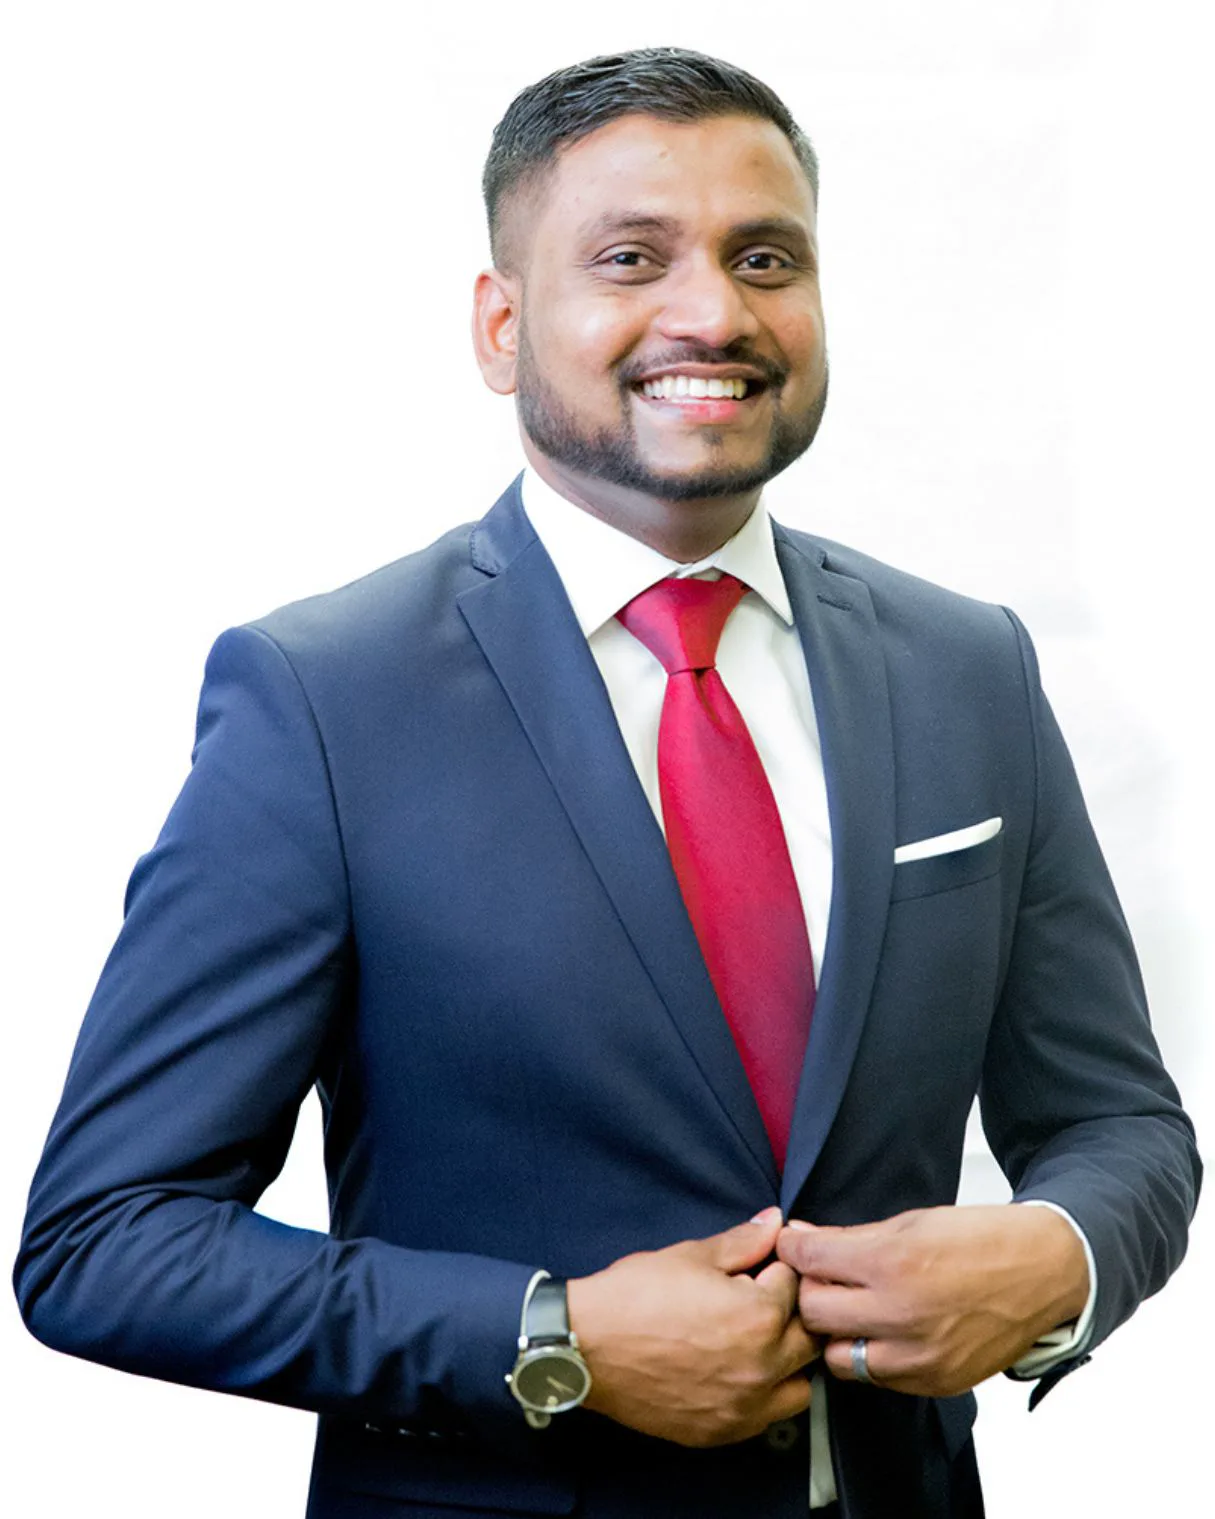
Amalan Mahendran — AT Financial Group. Licensed life insurance advisor in Ontario. Eighteen years in insurance and real estate; based in Pickering; works with physicians and dentists across Durham Region and the GTA. Also a Sales Representative with The Agency, Brokerage.
Both are licensed in Ontario; licence numbers are on .
The evening
- 5:00 pm
Arrive, drinks, introductions. Who is in the room and what they came to ask.
- 5:30 pm
Dinner is served. Topics one and two, with the $1.5 million example on the screen.
- 6:30 pm
Topics three to six. Questions as they come, not at the end.
- 7:15 pm
Coffee. The one-page comparison, and how to get your own.
- 8:00 pm
Close. Nobody is held back.
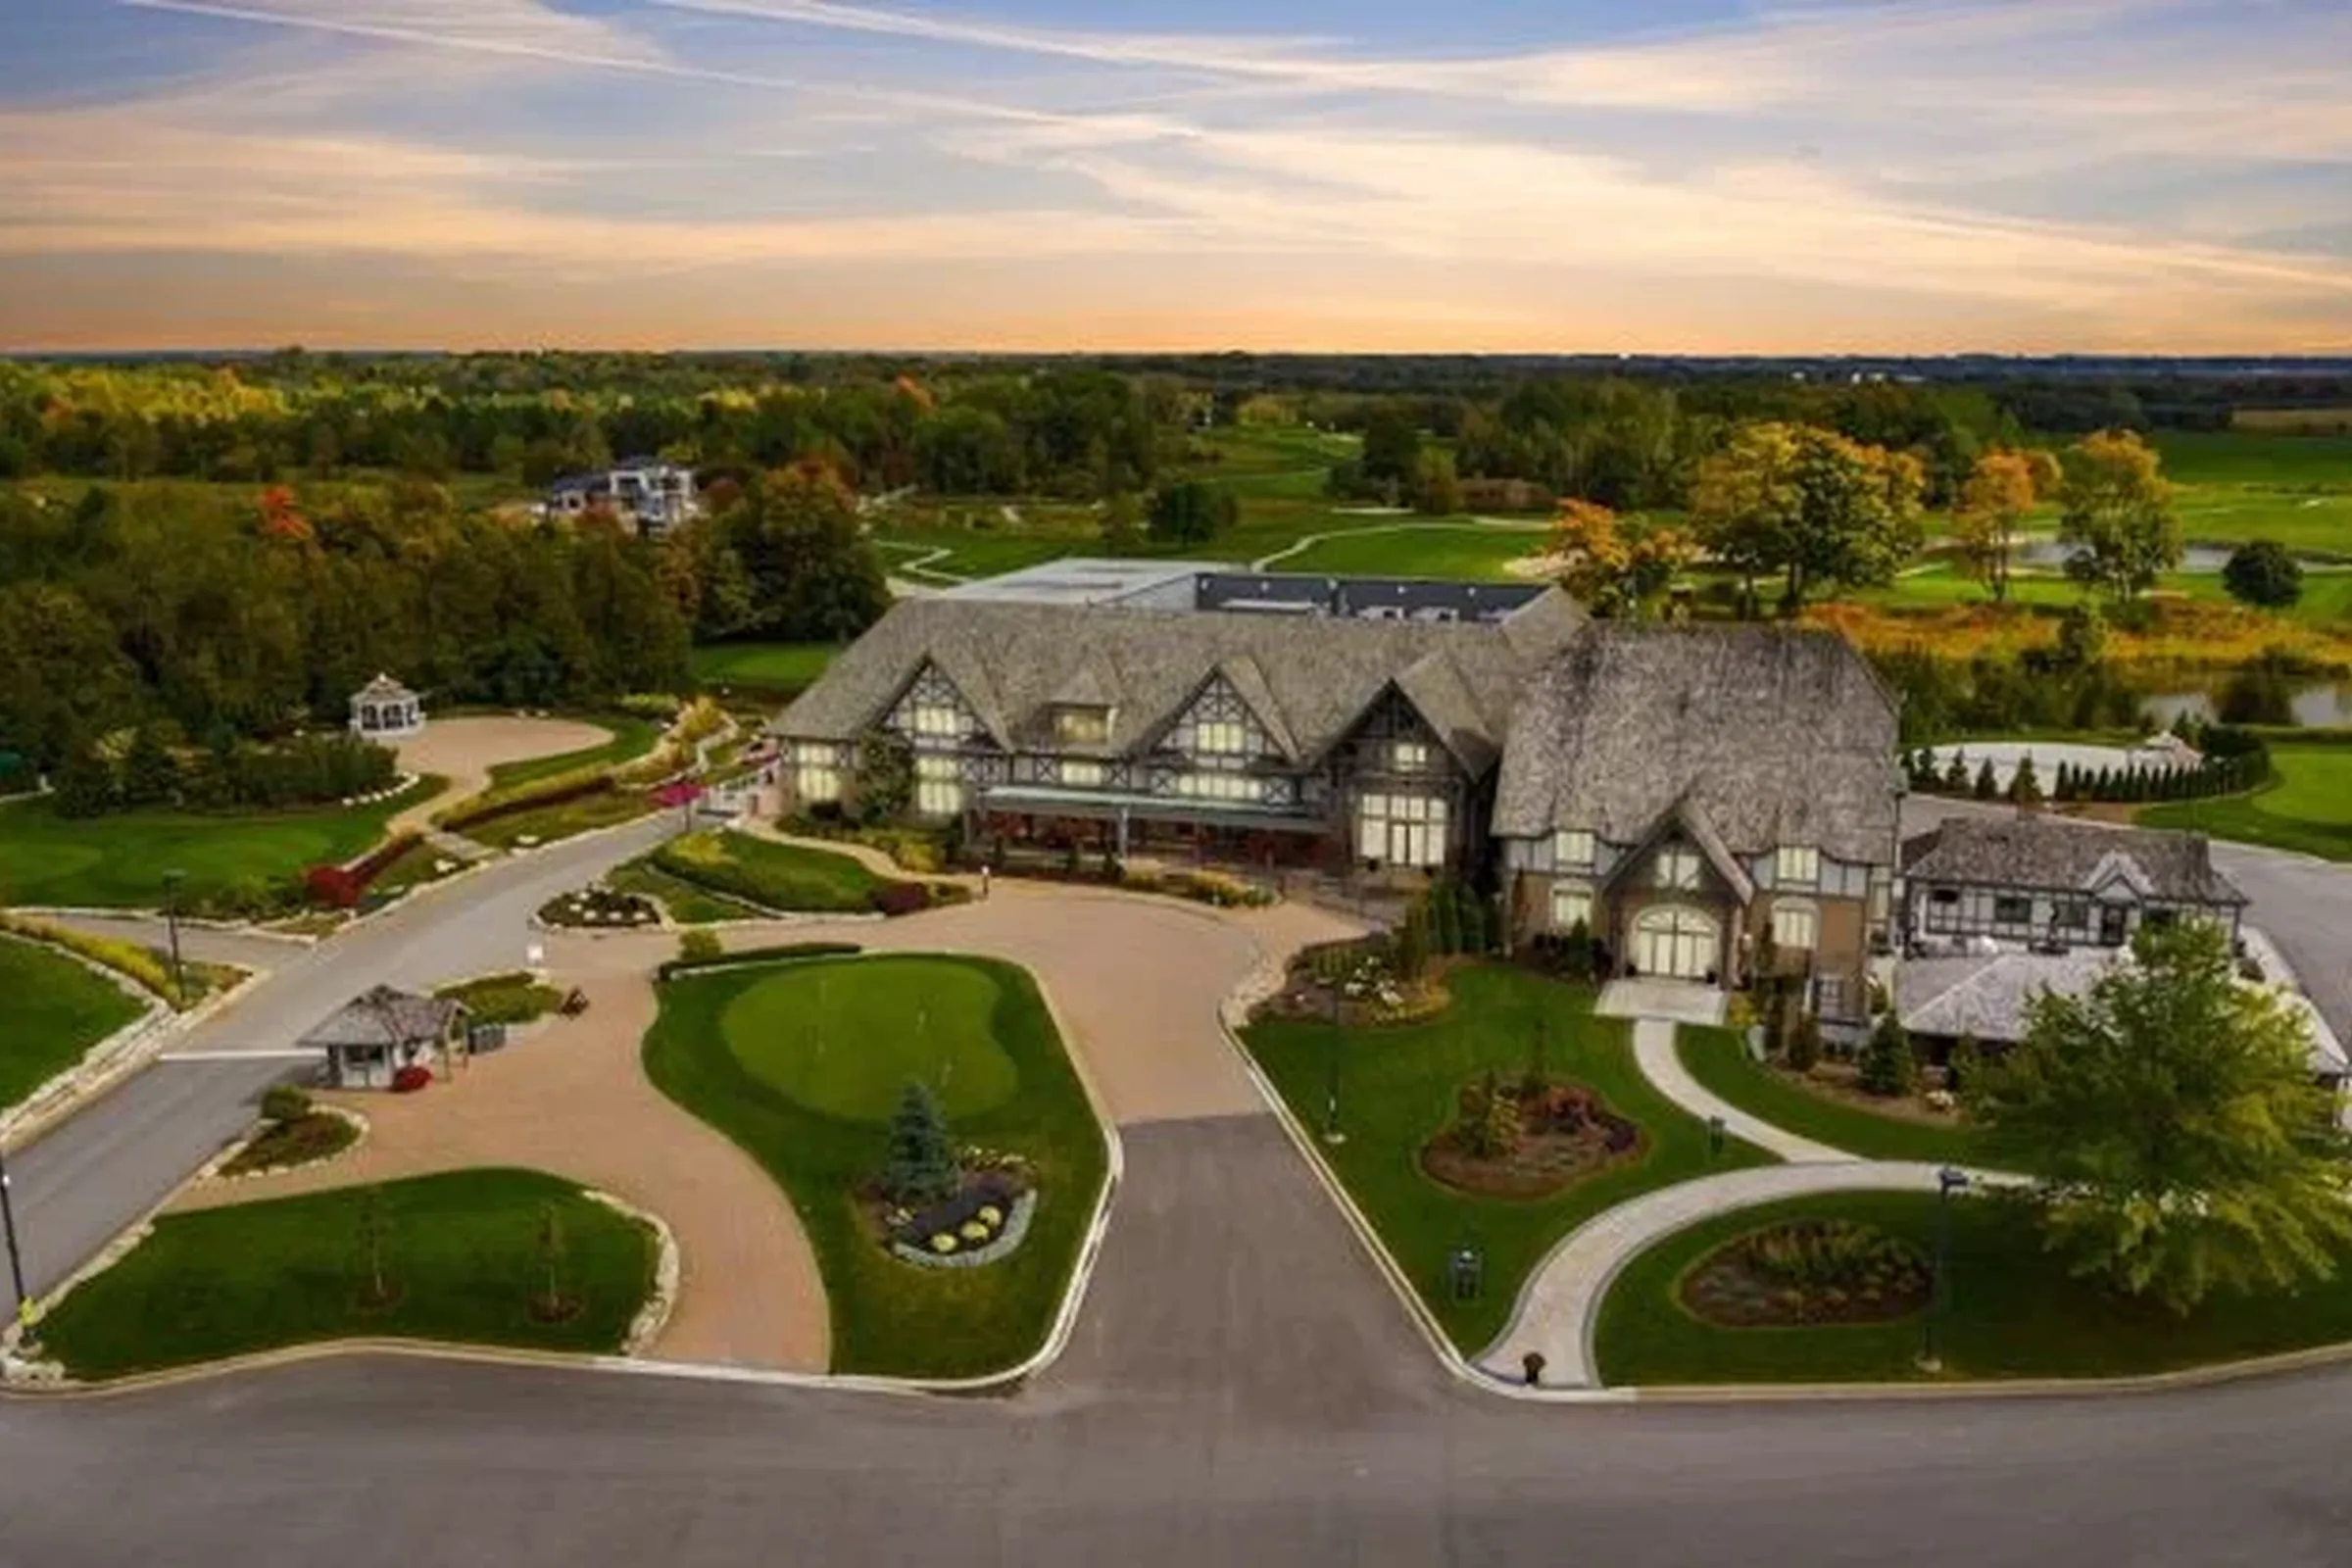
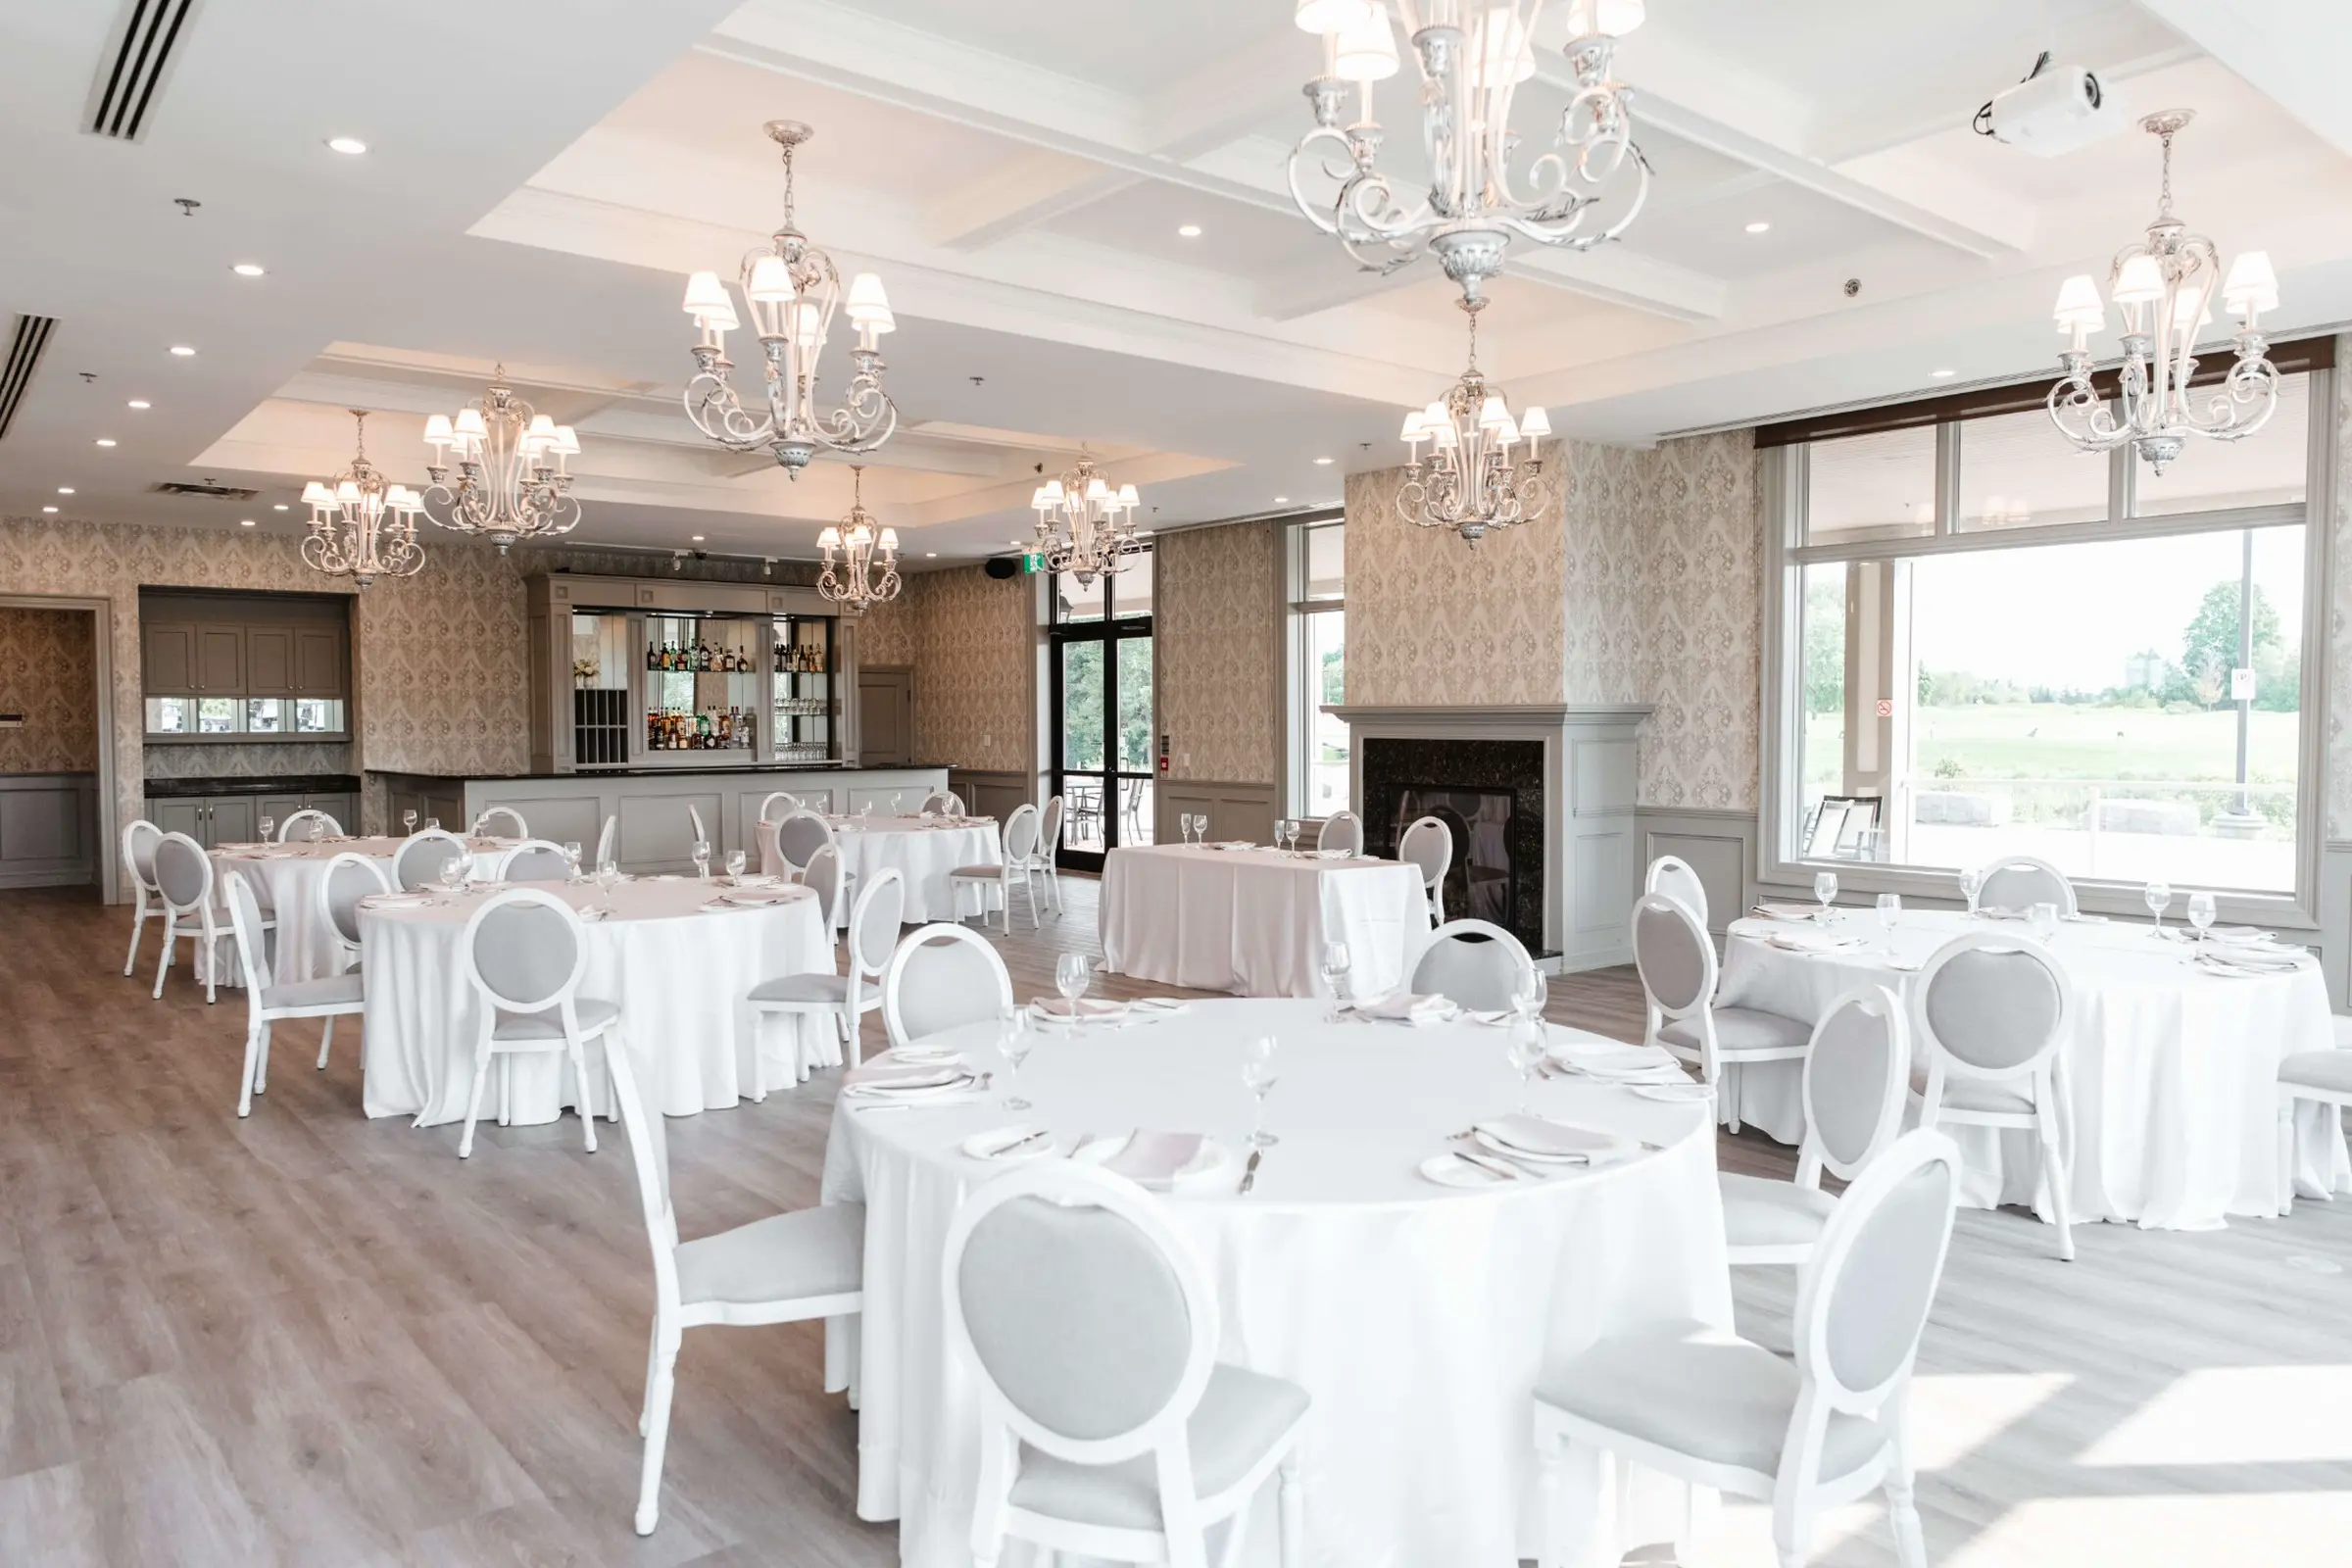
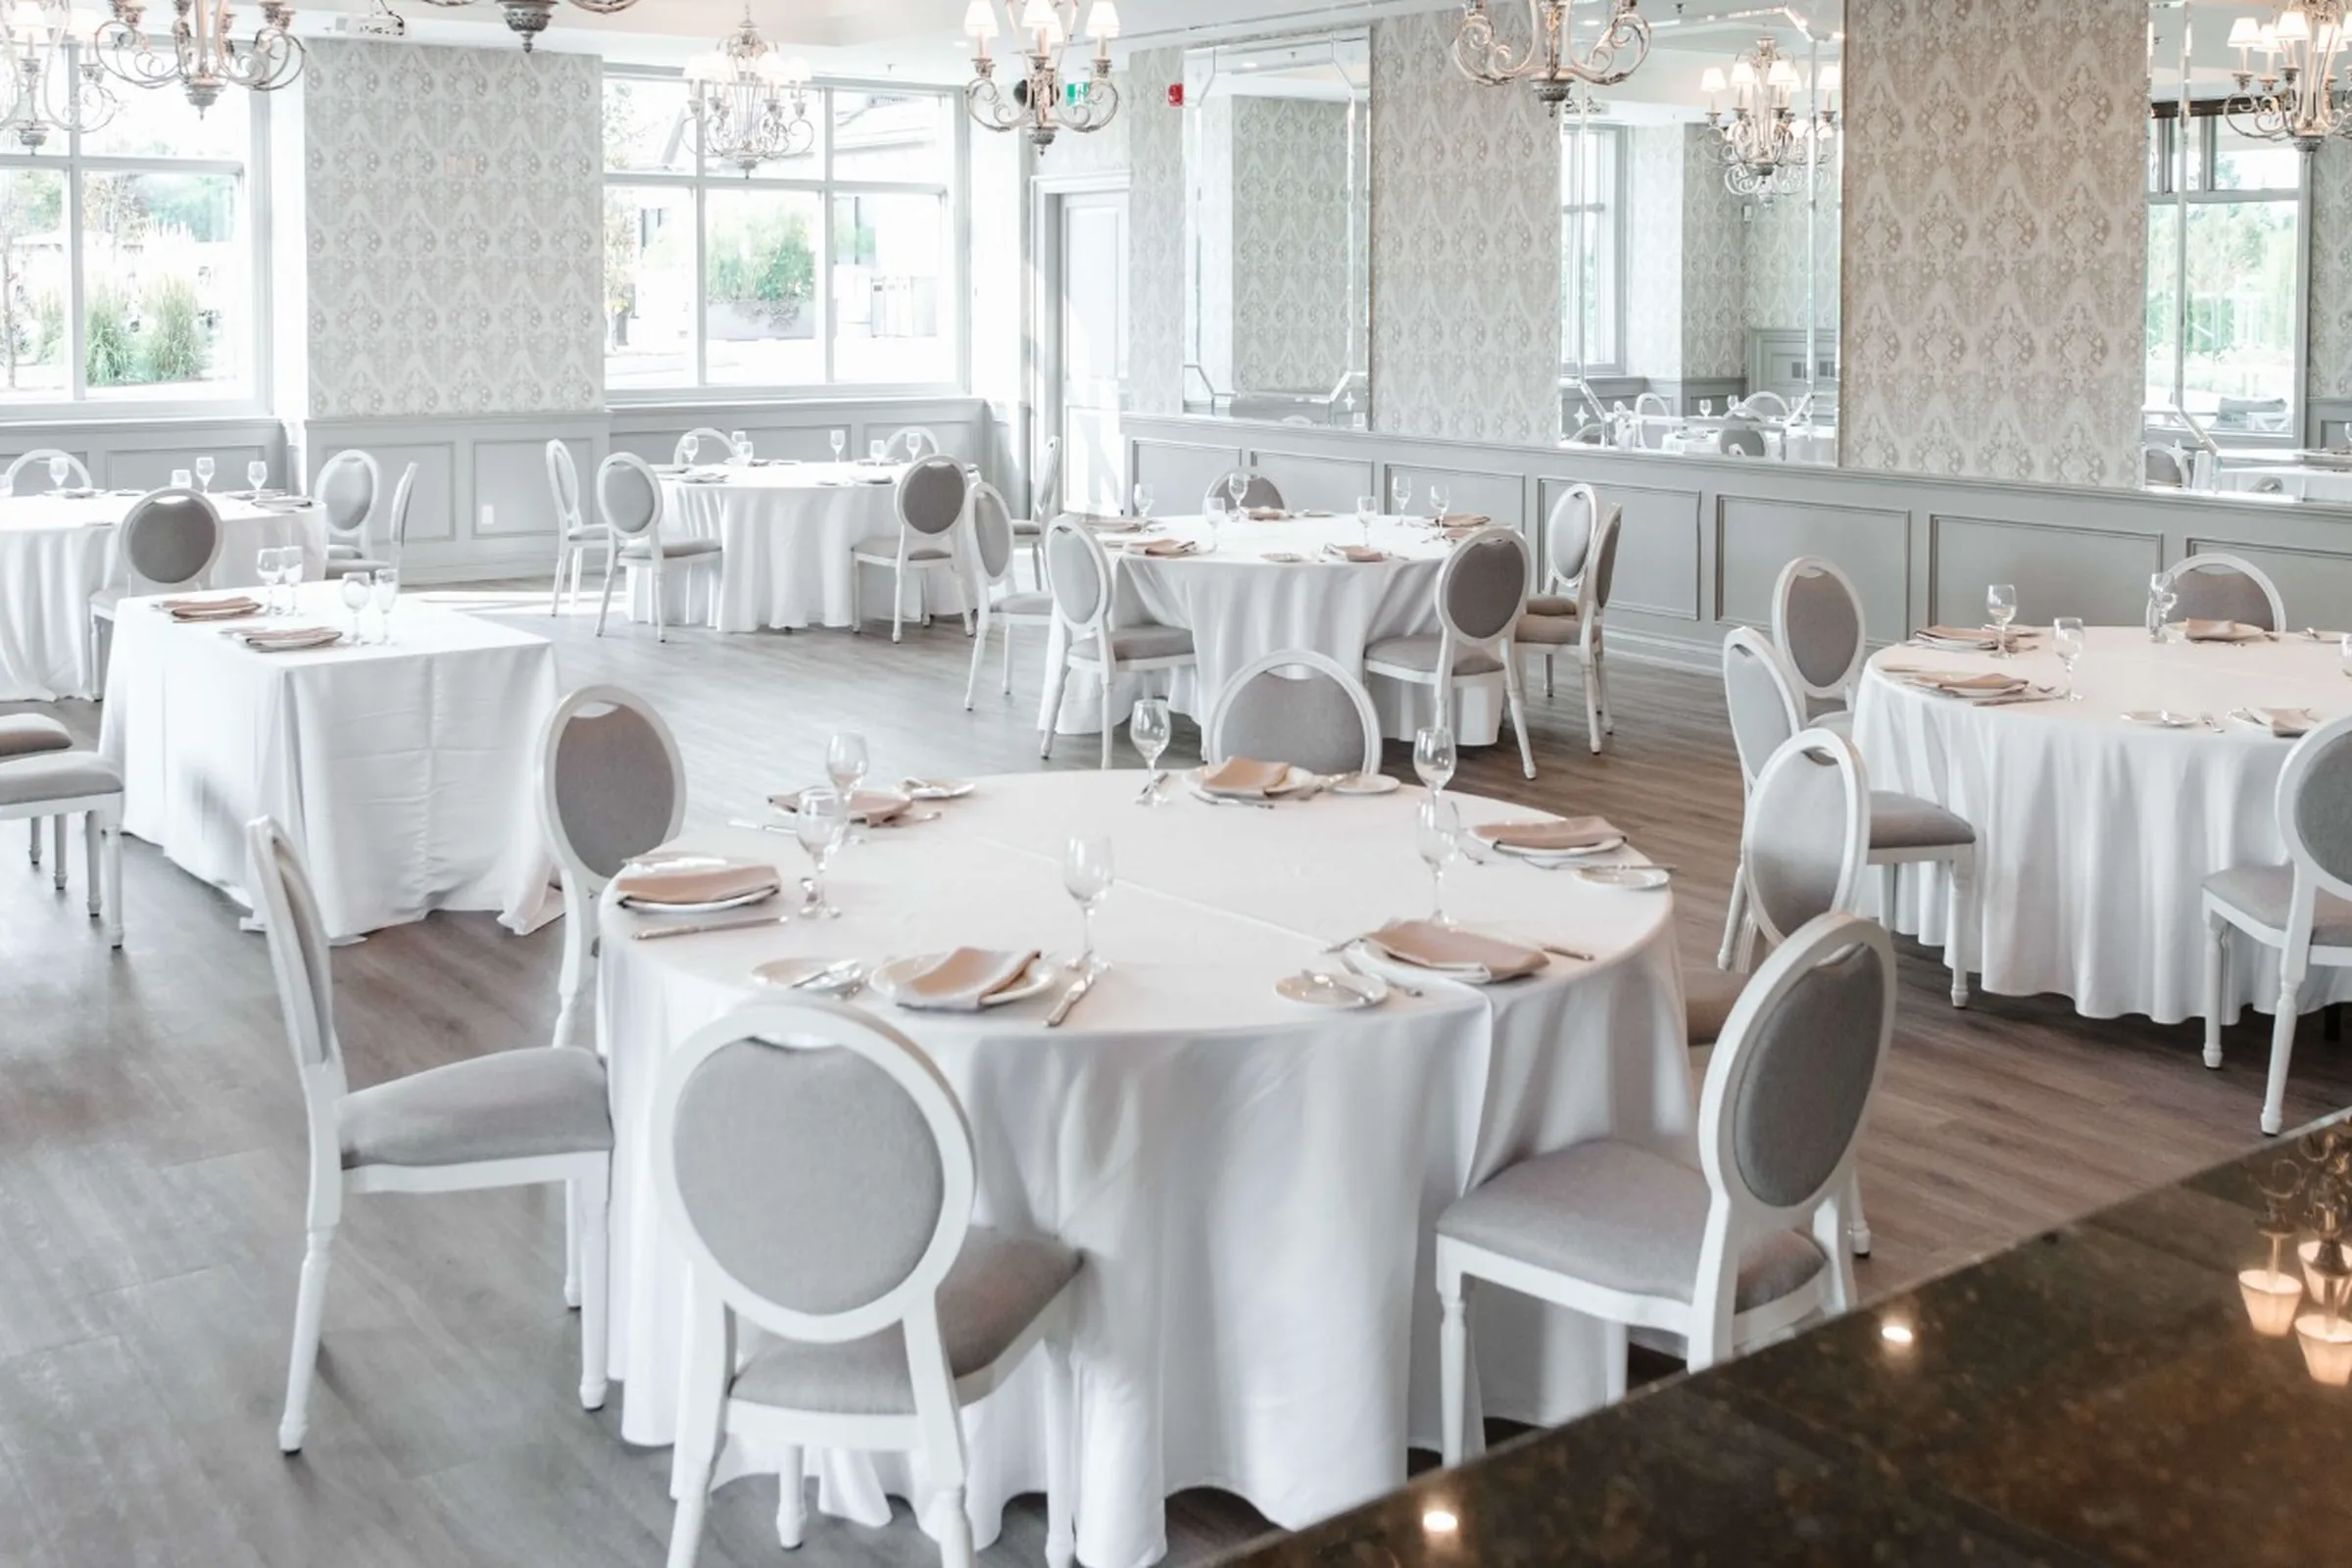
Thirty seats, so the table stays a conversation. Venue: Deer Creek, Ajax. Dinner and parking are on AT Financial Group.
The calendar file comes with your seat confirmation
Frequently asked
Is there a cost?
No. AT Financial Group hosts the dinner. There is no obligation afterwards.
Can my spouse or partner come?
Yes. Tell us on the form so we hold two seats.
Is it a sales presentation?
No. It is two advisors explaining trade-offs with Ontario 2026 figures. No product is named as best and nothing is signed at the table.
Who else will be there?
Physicians and dentists from Durham Region and the GTA. Seats are capped at 24. We do not share the guest list.
I am a dentist; is this only for physicians?
It is for both. The corporation rules differ in places (RCDSO vs CPSO, the practice sale, CDSPI vs OMA coverage) and we cover both.
Will you keep my details?
Only to confirm your seat and send the handout. You can ask us to delete them at any time. Our privacy page explains the rest.
What if I cannot make November 7th?
Register for the next dinner at the end of this page and you will get the next date first.
Does it count for CME or CE?
Not as a certified activity. Some physicians self-report; check your College's rules.
Not this date? Get the next invitation first.
This is not a seat at the Saturday, November 7th, 2026 dinner. If you cannot make that date, register here and you will be the first to hear about the next one.